 listicle
Used Car Dealership With Financing: 10 Top Options
Table of Contents
- Quick Comparison: 10 Used Car Dealerships With Financing
- 1. DriveTime: High Approval Rates for All Credit Types
- 2. Rick Hendrick Buick GMC: Manufacturer-Backed Financing for Certified Pre-Owned
- 3. Atlanta Best Used Cars: Soft-Pull Pre-Approval Without Credit Impact
- 4. Nalley Automotive: Multi-Brand Inventory With Home Delivery
- 5. MasterCars Auto Sales: In-House Financing for Credit Challenges
- 6. Auto Now KC: Specialized Bad Credit Auto Loans
- 7. Don Hattan Chevrolet: Lender Network for Rate Shopping
- 8. Jim Ellis Buick GMC: Financing After Bankruptcy
- 9. Advantedge Quality Cars: Straightforward Financing for Every Credit Tier
- 10. Davis-Moore Auto Group: Expert Guidance on Loan Terms
- What Documents Do You Need for Car Financing?
- How the Auto Loan Pre-Approval Process Works
- Frequently Asked Questions
Last Updated: September 15, 2026
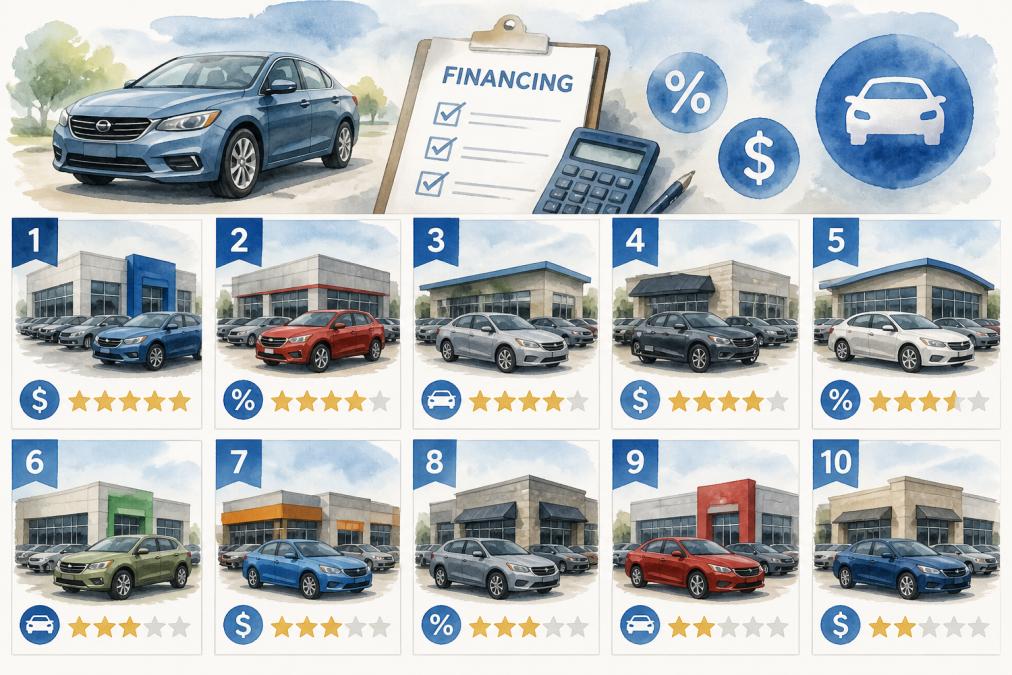
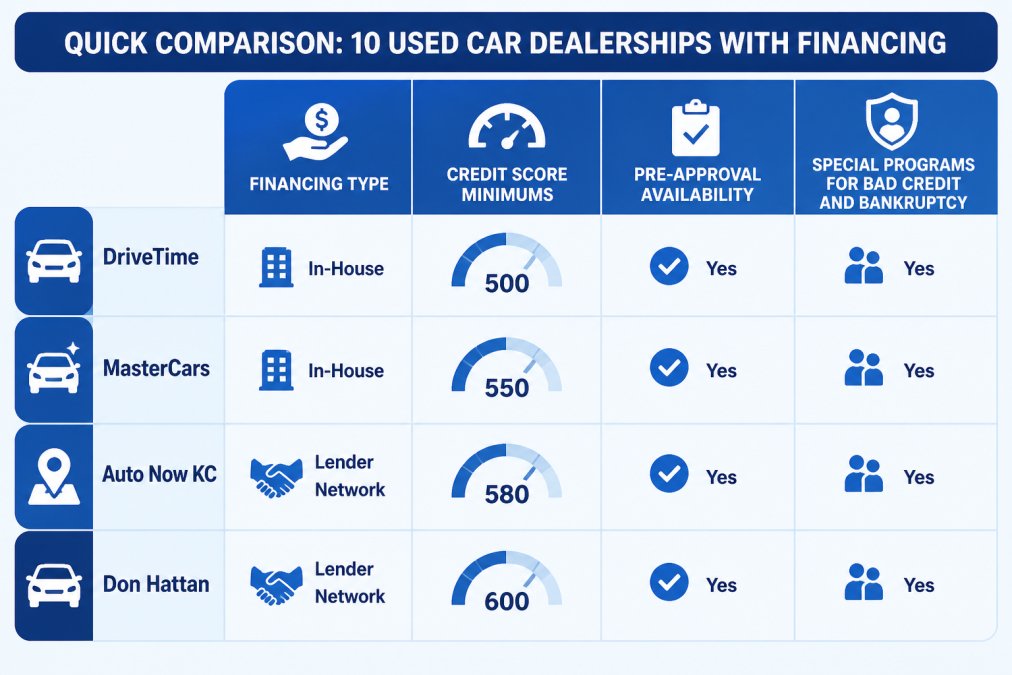
Quick Comparison: 10 Used Car Dealerships With Financing
Finding a used car dealership with financing that actually approves you is the difference between driving home this week and starting over. Approval odds depend far more on which dealership you walk into than on your credit score alone. This guide compares ten dealerships on financing type, credit flexibility, and pre-approval speed.
| Dealership | Financing Type | Credit Flexibility | Pre-Approval |
|---|---|---|---|
| DriveTime | National lender network | All credit types | Online |
| Rick Hendrick Buick GMC | Manufacturer-backed | Credit-dependent | Online |
| Atlanta Best Used Cars | Third-party lenders | Moderate | Soft-pull online |
| Nalley Automotive | Multi-lender | Moderate | Online |
| MasterCars Auto Sales | In-house | Credit challenges | In-store |
| Auto Now KC | In-house | Bad credit focus | In-store |
| Don Hattan Chevrolet | 50+ lender network | All tiers | Online |
| Jim Ellis Buick GMC | Lender network | Bankruptcy accepted | Online |
| Advantedge Quality Cars | In-house | All credit types | Online |
| Davis-Moore Auto Group | Lender network | Credit-dependent | Online |
1. DriveTime: High Approval Rates for All Credit Types
DriveTime built its business around buyers traditional banks reject. The chain finances in-house through its own lending arm, which means approval decisions don't depend on a bank's credit score cutoff. Their online pre-qualification takes a few minutes and doesn't require a hard credit pull upfront. The trade-off is honest: rates run higher than a prime bank loan, and inventory skews toward older, higher-mileage vehicles. For someone rebuilding credit who needs reliable transportation now, that's often an acceptable exchange.
2. Rick Hendrick Buick GMC: Manufacturer-Backed Financing for Certified Pre-Owned
Manufacturer-backed financing through a franchised dealership is the strongest option if your credit is decent. Rick Hendrick Buick GMC pairs certified pre-owned inventory with factory lending programs, and certified vehicles typically include manufacturer-backed extended warranty coverage. Approval is subject to credit qualification, so this isn't the route for serious credit challenges. Get both manufacturer and dealer-arranged quotes before signing.
3. Atlanta Best Used Cars: Soft-Pull Pre-Approval Without Credit Impact
A soft-pull credit check lets you see your approval odds without the inquiry appearing on your credit report. Atlanta Best Used Cars offers this through a self-paced online application, which matters if you're rate-shopping across several dealerships and want to avoid stacking hard inquiries. The limitation is geographic: inventory is regional, so buyers outside the area won't find a match.
4. Nalley Automotive: Multi-Brand Inventory With Home Delivery
Nalley Automotive carries multiple brands under one roof and lets you complete pre-approval online, then choose home delivery or dealership pickup. Financing terms vary by lender and credit profile, so the rate you see in pre-approval can shift once a finance manager runs the full application.
5. MasterCars Auto Sales: In-House Financing for Credit Challenges
In-house financing means the dealership is the lender, not a middleman. MasterCars Auto Sales runs guaranteed approval programs for buyers with credit challenges, skipping the third-party bank hurdles that cause most denials. Expect a higher down payment than a bank loan, but more room to negotiate terms directly.
6. Auto Now KC: Specialized Bad Credit Auto Loans
Bad credit auto loans are this dealership's entire focus. Auto Now KC processes loans in-house and keeps an inventory of used cars, trucks, and SUVs aimed at buyers rebuilding credit. Approval turnaround is fast because there's no outside lender to wait on. The catch is geography: service is limited to specific areas, so check coverage before applying.
7. Don Hattan Chevrolet: Lender Network for Rate Shopping
Don Hattan Chevrolet shops your application across a network of more than 50 lenders and provides rate comparison tools, so you get rate competition without the legwork. Approval still depends on your credit standing, and multiple applications can generate multiple inquiries, ask them to shop within a short window so the inquiries count as one shopping period.
8. Jim Ellis Buick GMC: Financing After Bankruptcy
Bankruptcy doesn't have to end your car search. Jim Ellis Buick GMC accepts all credit situations, including open bankruptcies and no-credit buyers, with online application tools. Terms and rates are individualized, so two buyers with similar histories can walk away with very different contracts. Bring your discharge paperwork and proof of income to speed things up.
9. Advantedge Quality Cars: Straightforward Financing for Every Credit Tier
Advantedge Quality Cars offers financing for good, bad, or no credit, paired with transparent vehicle history reporting, and handles financing guidance in-house. Inventory fluctuates, so call ahead before making the trip.
10. Davis-Moore Auto Group: Expert Guidance on Loan Terms
Loan structure matters as much as the rate. Davis-Moore Auto Group staffs its finance department to walk buyers through term length, down payment trade-offs, and total interest cost before signing, stretching a loan to lower the monthly payment often raises what you pay overall. Terms are subject to credit approval, and pre-owned inventory is large enough to give you real choices.
What Documents Do You Need for Car Financing?
Most dealerships ask for the same core paperwork, but the exact list depends on whether you finance through a bank or credit union, a dealer's lender network, or the dealership's in-house program. Having the right stack ready before you apply is the single biggest thing you can do to shorten approval.
Here is the working checklist. Print it or screenshot it before you go.
Identity and residency
- Valid driver's license or state-issued ID (unexpired)
- Proof of residence dated within the last 30-60 days: utility bill, lease agreement, mortgage statement, or a piece of official mail
- Social Security number (you will provide it on the application, not as a document)
Income verification
- Most recent 30 days of pay stubs, or the last two pay stubs if you are paid biweekly
- Last two months of bank statements if you are paid in cash or are self-employed
- Most recent W-2, or the last two years of tax returns if you are self-employed, 1099, or a business owner
- Proof of any secondary income you want counted: disability, retirement, alimony, or child support
Insurance and references
- Current auto insurance card or policy number, most lenders will not release the vehicle without proof of coverage
- Six to eight personal references with name, phone number, and relationship, for in-house and Buy Here Pay Here programs
Down payment and trade-in
- Down payment funds in a form the dealer accepts (cashier's check, debit card, or verified bank transfer)
- Your trade-in's title, registration, and payoff information if it is still financed
Why In-House Financing Asks for More
When a dealership lends you money directly, it carries the entire risk of the loan on its own books. A bank can spread risk across thousands of loans; a single dealership cannot.
If You Are Self-Employed, Paid in Cash, or Newly Employed
A Note on Co-Signers
How the Auto Loan Pre-Approval Process Works
Soft Pull vs. Hard Pull: What Actually Happens to Your Credit
How In-House and Buy Here Pay Here Loans Report to the Credit Bureaus
What to Ask Before You Sign
A Word on Predatory Terms
Frequently Asked Questions
Will a dealership finance a used car?
Yes, most dealerships offer used car financing through in-house programs, manufacturer-backed loans, or a network of lenders. Franchised dealers like Rick Hendrick Buick GMC and Don Hattan Chevrolet work with multiple banks, while Buy Here Pay Here lots like MasterCars Auto Sales provide direct in-house loans. Approval depends on your credit score, income, down payment, and the vehicle's age and mileage. Even with bad credit, many dealerships have programs designed to get you approved.
Is it hard to get financed for a used car?
It's not necessarily hard, but it depends on your credit profile and the dealership. Traditional banks often require a credit score of 600 or higher, while Buy Here Pay Here dealerships and those specializing in used car financing for bad credit may approve applicants with scores below 500. Having a stable income, a down payment, and documents ready can improve your chances. Online pre-approval tools let you check eligibility without impacting your credit score.
What documents do I need for dealership financing?
You'll typically need a valid driver's license, proof of income (pay stubs or bank statements), proof of residence (utility bill or lease), and your Social Security number. Some dealerships may also ask for references, proof of insurance, or a down payment. Having these documents ready speeds up the auto loan pre-approval process. If you're self-employed, bring tax returns or bank statements. Always ask the finance department for a complete list before you visit.
How does in-house financing differ from bank loans?
In-house financing means the dealership acts as the lender, so you make payments directly to them. This option is easier to qualify for, especially with bad credit, but interest rates may be higher. Bank loans typically offer lower rates for qualified buyers but require stronger credit. In-house financing can help rebuild credit if you make on-time payments. Weigh the total cost of ownership, including interest and fees, before choosing.