 how-to
How to Get Pre-Approved for a Car in Toms River
Table of Contents
- What Pre-Approval Means and Why It Matters
- Documents Needed for Car Loan Pre-Approval
- Car Loan Pre-Approval Credit Score Impact
- Car Loan Pre-Approval Process and Timeline
- Online Auto Financing Application
- Common Mistakes to Avoid During Pre-Approval
- What Happens After You're Pre-Approved
- Frequently Asked Questions
Last Updated: October 5, 2026
What Pre-Approval Means and Why It Matters
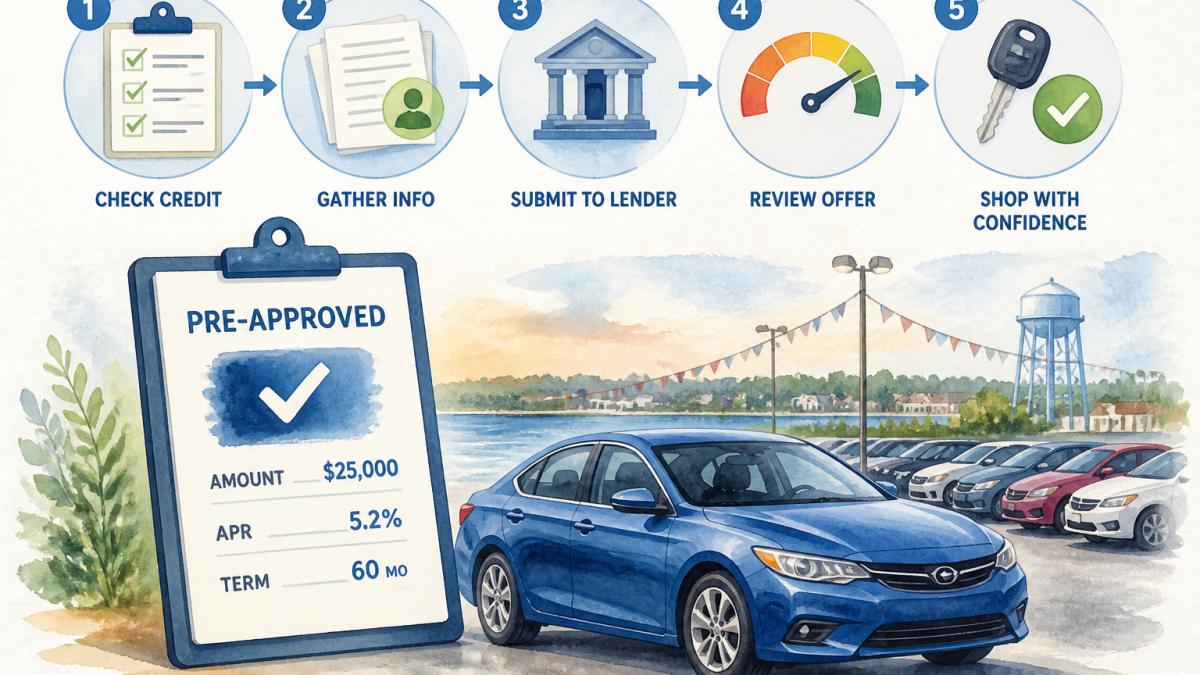
Being pre-approved for a car is a lender's conditional promise to loan you a specific amount of money for your purchase. It's not a guarantee, but it's a strong signal that you qualify for financing at a certain price point. We help buyers understand how pre-approval works because it transforms the entire car-buying process.
When you're pre-approved for a car, you walk into negotiations with power. You know your budget. You know your interest rate. You're not scrambling to find financing after you've already fallen in love with a vehicle. That clarity matters.
Pre-approval also protects you from overspending. Many buyers get emotional on the lot and stretch beyond their means. Pre-approval sets a hard ceiling. You can't exceed it, which keeps your monthly payments realistic and your finances stable.
Documents Needed for Car Loan Pre-Approval
Lenders need proof of three things: who you are, how much you earn, and how you've handled debt in the past. Gather these documents before you apply.
Income and Employment Verification
Lenders want to see that you earn enough to make monthly payments. Bring recent pay stubs covering the last 30 days. If you're self-employed, prepare your last two years of tax returns and a current profit-and-loss statement.
Some applicants have irregular income. If you work commission or seasonal jobs, lenders may average your earnings over two years. Bring documentation that shows your income pattern.
If you're recently employed, bring an offer letter from your employer. Some lenders require 90 days of employment history, but many will work with you if the job is stable.
What to bring:
- Two most recent pay stubs
- W-2 forms from the last two years
- Tax returns (if self-employed)
- Offer letter (if newly hired)
- Proof of employment letter from your employer
Credit and Financial Documentation
Lenders pull your credit report automatically, but you should understand what they're looking at. Your credit score, payment history, and outstanding debts all factor into approval and interest rates.
Bring recent bank statements showing 30-60 days of activity. Lenders want proof that you have funds available and manage your accounts responsibly. They're looking for stable account balances and regular deposits.
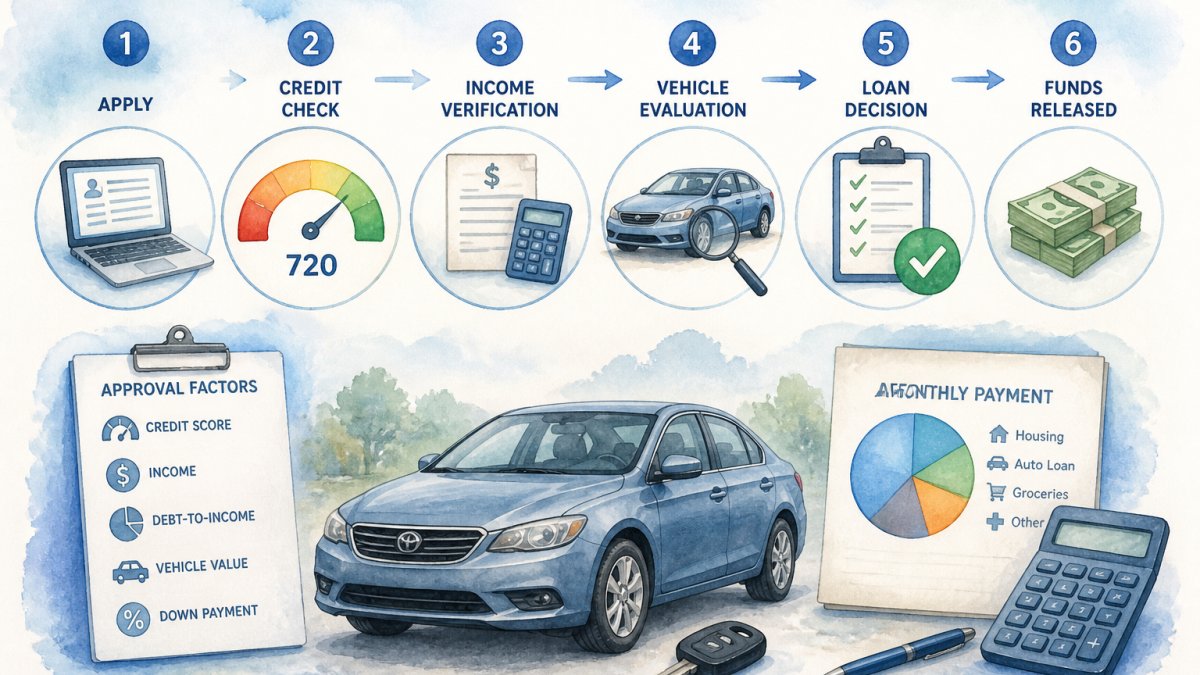
If you have other debts, car loans, student loans, credit cards, list them with current balances. Lenders calculate your debt-to-income ratio. If you owe too much relative to your income, approval becomes harder.
What to bring:
- Government-issued ID
- Social Security card or number
- Recent bank statements (30-60 days)
- List of current debts and balances
- Proof of address (utility bill or lease)
Car Loan Pre-Approval Credit Score Impact
Your credit score affects whether you get approved and what interest rate you'll pay. Many buyers worry that applying for pre-approval will damage their score. The truth is more nuanced.
When a lender pulls your credit, it's called a "hard inquiry." Hard inquiries lower your score by a few points, typically 5-10 points. That's temporary. Your score rebounds within a few months as long as you don't miss payments.
Multiple applications within 14 days count as a single inquiry for scoring purposes (Credit Scores). If you apply with three lenders in one week, the impact is roughly the same as applying with one lender. This is called "rate shopping," and credit bureaus recognize it as normal behavior.
The real damage comes from missed payments or maxed-out credit cards. Pre-approval itself doesn't hurt you. Irresponsible behavior after pre-approval does.
Your credit score also determines your interest rate. Borrowers with scores above 750 typically get the best rates. Scores between 650-749 see higher rates. Below 650, approval becomes difficult, though not impossible. Some lenders specialize in working with lower credit scores.
Car Loan Pre-Approval Process and Timeline
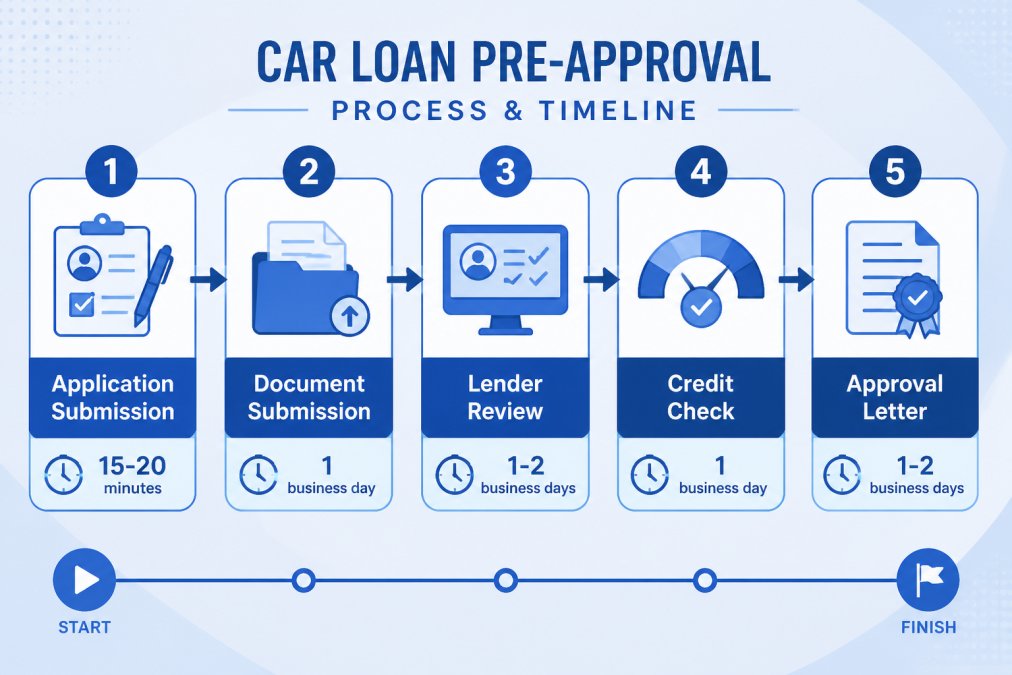
The pre-approval process typically takes 2-5 business days from application to approval letter. Speed depends on how quickly you submit documents and how straightforward your financial situation is.
Step-by-Step Pre-Approval Walkthrough
Step 1: Complete the application. You'll fill out a form with basic information: name, address, employment, income, and existing debts. This takes 15-20 minutes. Be accurate. Lenders verify everything.
Step 2: Submit financial documents. Upload or email your pay stubs, bank statements, and ID. Most lenders have online portals for this. Submitting quickly speeds up the process.
Step 3: Lender reviews your application. This typically takes 1-2 business days. The lender verifies your employment, checks your bank balances, and reviews your credit report. They calculate your debt-to-income ratio and determine how much they'll lend.
Step 4: Credit check is completed. The lender pulls your credit report and score. This happens automatically during the review process.
Step 5: Approval decision is made. You'll hear back within 2-5 business days. Approval letters specify the loan amount, interest rate, and loan term.
Online Auto Financing Application
Many lenders, including AutoSport USA, offer online applications. Online applications are faster and more convenient than visiting a bank branch.
Online applications walk you through the process step-by-step. You'll enter your personal information, employment details, and financial data. Most applications take 15-25 minutes to complete.
After you submit, you'll upload documents through a secure portal. This is safer than emailing sensitive financial information. Most platforms show you real-time status updates so you know where your application stands.
Some online lenders offer same-day decisions. Others take the standard 2-5 business days. Check the lender's timeline before you apply so you know what to expect.
Why online works better:
- No branch hours to work around
- Upload documents anytime
- Track progress in real time
- Faster decisions than in-person applications
- You can apply from home
Common Mistakes to Avoid During Pre-Approval
Many applicants hurt their own chances by making preventable errors. Here are the biggest pitfalls.
Applying with multiple lenders in a short window. You should shop around, but do it within 14 days. Spacing applications further apart creates multiple hard inquiries that damage your score.
Overstating your income. Lenders verify everything. If your application says you earn more than you actually do, the verification fails and your application gets denied. Be honest.
Ignoring existing debt. Don't hide credit cards, student loans, or other obligations. Lenders find them anyway during the credit check. Honesty builds trust and speeds approval.
Applying while carrying high credit card balances. Your debt-to-income ratio matters. If you're maxed out on credit cards, your ratio looks bad. Pay down balances before applying if you can.
Changing jobs right before applying. New employment looks risky to lenders. If you've just changed jobs, wait 90 days before applying. Stability matters.
Making large purchases after applying. New debt increases your debt-to-income ratio and can flip an approval to a denial. Wait until after you're approved to make big purchases.
What Happens After You're Pre-Approved
Once you have a pre-approval letter, you're ready to shop. The letter specifies your loan amount, interest rate, and loan term. These numbers are locked in for a set period, usually 30-90 days.
When you find a vehicle you want, your pre-approval letter tells the dealer exactly what you can spend. This gives you negotiating power. You're not waiting for financing to come through, it's already arranged.
The dealer will verify your pre-approval and process the final paperwork. The actual loan gets funded after you've signed all documents and passed a final inspection of the vehicle. This typically happens within 24-48 hours.
Your pre-approval is conditional. The lender can still pull out if your financial situation changes dramatically or if the vehicle doesn't meet their standards. But for most buyers, pre-approval leads straight to a funded loan.
Our online financing tools let you see what you qualify for before you shop, so you know your budget and can focus on finding the right vehicle for your needs.
Frequently Asked Questions
What documents do I need to get pre-approved for a car loan?
You'll typically need proof of income (recent pay stubs or tax returns), employment verification, a government-issued ID, proof of residence (utility bill or lease), and authorization for a credit check. Some lenders may also request bank statements or proof of down payment funds. Having these documents ready speeds up the pre-approval process significantly.
Does getting pre-approved for a car loan affect my credit score?
A pre-approval inquiry causes a small, temporary dip in your credit score, typically 5-10 points. This is a hard inquiry that lenders perform to assess your creditworthiness. However, multiple pre-approval inquiries within a short window (usually 14-45 days) count as a single inquiry, so shopping around for the best rate won't damage your score as much as you might think.
How long does car loan pre-approval take?
Pre-approval timelines vary by lender. Online applications can be processed in minutes to a few hours, while traditional bank pre-approvals may take 1-3 business days. Having your documents organized and ready beforehand significantly reduces waiting time.
Can I get pre-approved for a car loan with bad credit?
Yes, you can still get pre-approved with bad credit, though you may face higher interest rates or stricter terms. Dealerships and specialized lenders often work with borrowers who have credit challenges. Some options include finding a co-signer, saving for a larger down payment, or exploring credit unions, which sometimes offer more flexible lending criteria than traditional banks.
Getting pre-approved for a car removes uncertainty from the buying process. You'll know your budget, your interest rate, and your monthly payment before you step onto a lot. The application takes less than an hour, and approval comes within days. AutoSport USA's online financing tools make the process straightforward, apply online, upload your documents, and get a decision fast. Ready to move forward? Apply online today and get pre-approved so you can shop with confidence.